Car Insurance for Used Cars: Coverage Options, Costs, and Ways to Save
Kicking off with Car Insurance for Used Cars: Coverage Options, Costs, and Ways to Save, this opening paragraph is designed to captivate and engage the readers, providing a comprehensive overview of the topic.
Exploring the different coverage options, cost factors, and money-saving strategies for insuring used cars is essential for every car owner.
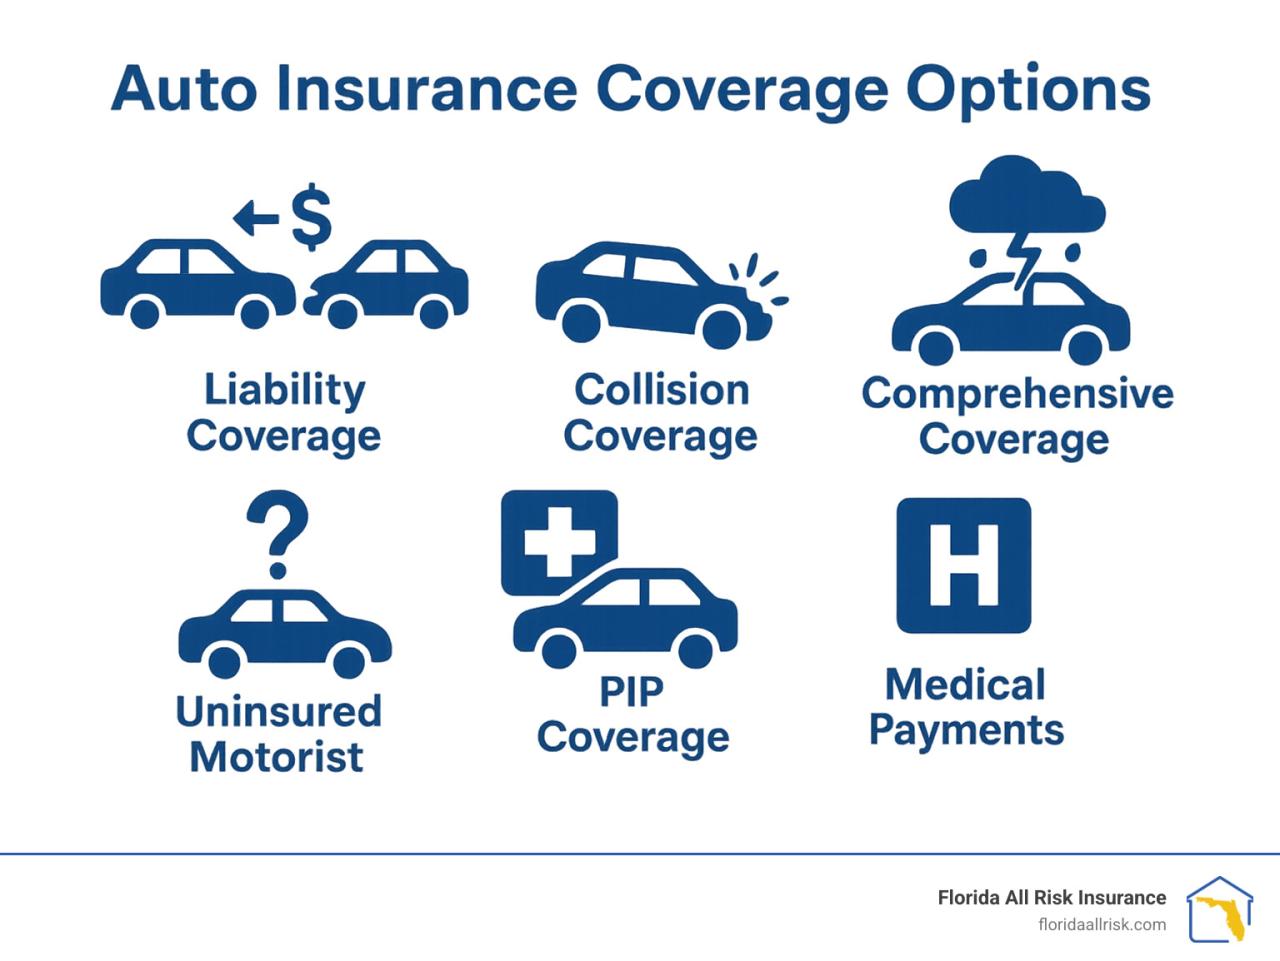
When it comes to insuring a used car, there are several coverage options available to protect you and your vehicle in case of an accident or other unforeseen events. Let’s take a look at some of the common types of coverage options for used cars.
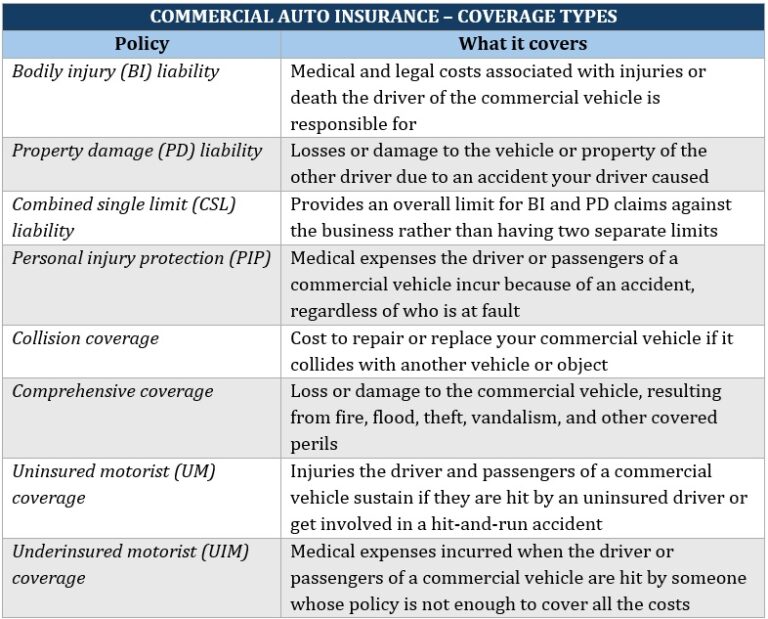
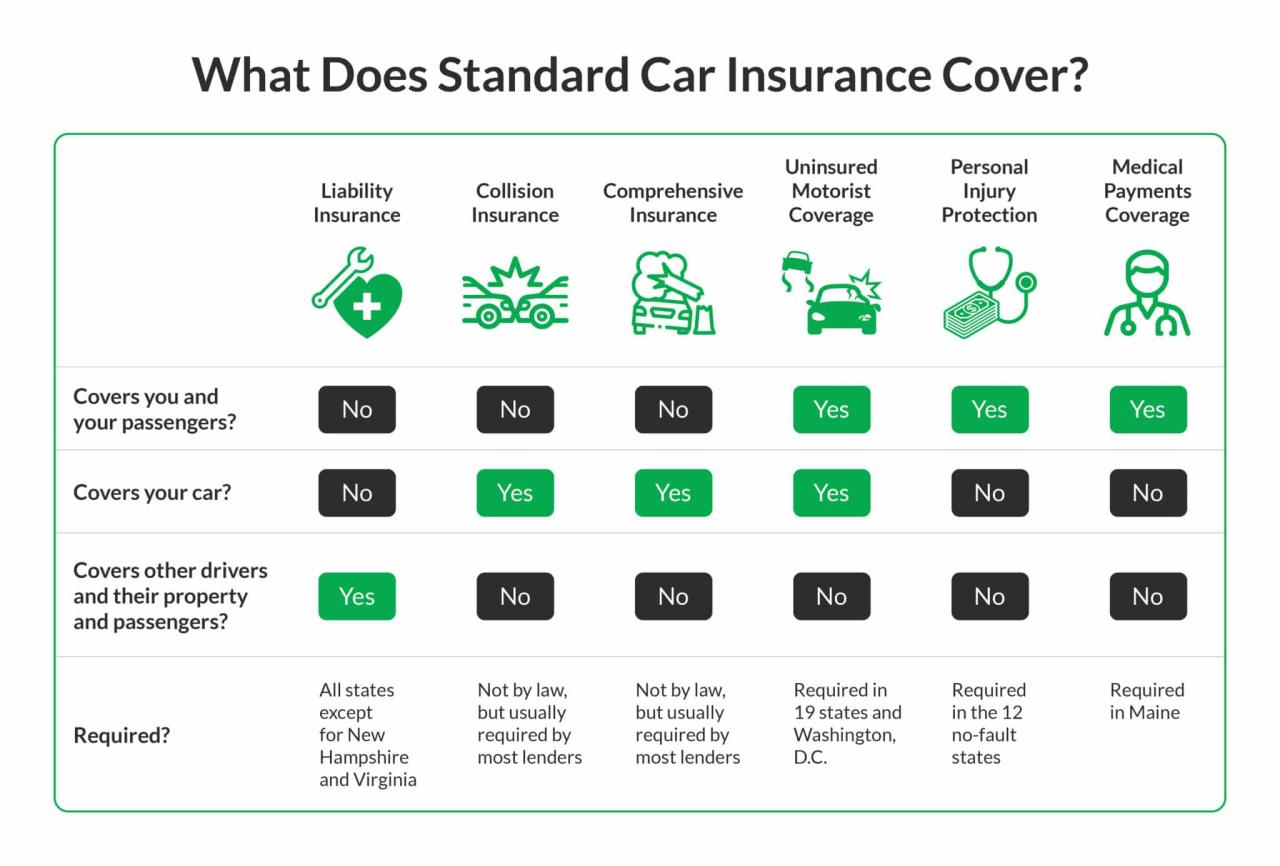
Comprehensive coverage provides protection for your vehicle in case of non-collision incidents, such as theft, vandalism, or natural disasters. This type of coverage can be beneficial for older vehicles that may not have a high resale value but are still important to you.
Liability coverage is required in most states and helps cover the costs of property damage and injuries to others in an accident that you are found responsible for. This coverage is essential for protecting your finances in case of a lawsuit resulting from an accident.
Uninsured/underinsured motorist coverage is crucial for older vehicles, as it helps cover the costs if you are in an accident with a driver who does not have insurance or enough insurance to fully cover the damages. This type of coverage can provide peace of mind knowing that you are protected even if the other driver is not adequately insured.
When it comes to determining the cost of car insurance for used cars, several factors come into play. These factors can significantly impact the premiums you pay for your coverage.
The age and condition of your used car play a crucial role in determining your insurance costs. Older cars typically have lower market values, which can result in lower premiums. However, if your car is in poor condition or lacks important safety features, your insurance costs may increase.
Insurers consider the likelihood of your car needing repairs or being involved in an accident when determining your premiums.
Your age, driving history, and location also play a significant role in determining your insurance costs. Younger drivers are often considered higher risk due to their lack of experience, leading to higher premiums. Additionally, drivers with a history of accidents or traffic violations may face increased insurance costs.
Your location can also impact your premiums, as areas with higher rates of accidents or theft may result in higher insurance costs.
When it comes to insuring your used car, there are several strategies you can use to save money on insurance premiums. Understanding these tips can help you make the most out of your insurance coverage while keeping costs manageable.
One effective way to save on car insurance for used cars is by bundling your insurance policies. By combining your auto insurance with other types of insurance, such as home or renters insurance, you can often qualify for a multi-policy discount.
This can result in significant savings on your overall insurance costs.
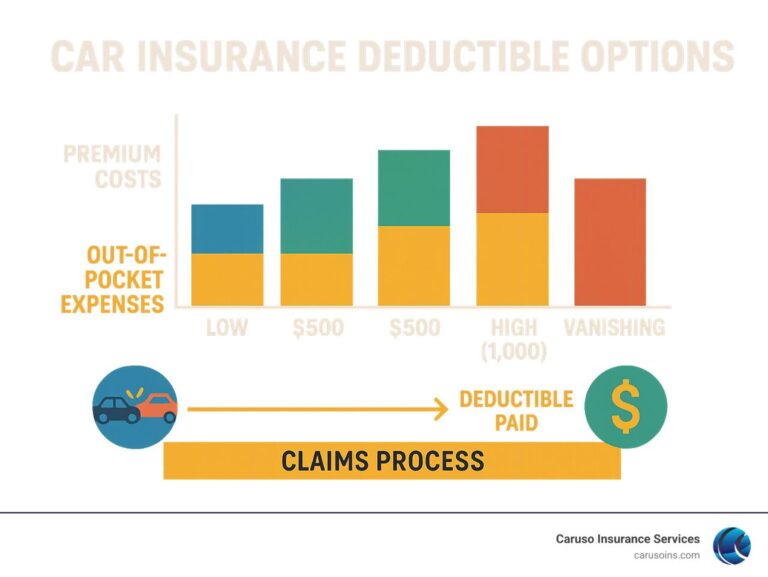
Another way to lower insurance costs for second-hand cars is by increasing your deductibles. By opting for a higher deductible amount, you can lower your monthly premiums. However, it’s important to ensure that you have enough savings set aside to cover the higher deductible in case of an accident.
What are the benefits of bundling insurance policies for used cars?
Bundling insurance policies for used cars can lead to discounts and cost savings, as insurance companies often offer lower rates for multiple policies held with them.
How does increasing deductibles lower insurance costs for second-hand cars?
Increasing deductibles for second-hand cars can reduce insurance premiums because higher deductibles mean you’ll pay more out of pocket in case of a claim, which decreases the risk for the insurance company.
Why is uninsured/underinsured motorist coverage important for older vehicles?
Uninsured/underinsured motorist coverage is crucial for older vehicles as it provides protection in case you’re involved in an accident with a driver who doesn’t have insurance or enough insurance to cover your damages.